Columnist’s relations with some senior editorial figures said to be strained over subjects she raised in her columns
The controversial Daily Telegraph columnist Allison Pearson is understood to be in negotiations about leaving the broadsheet as the newspaper’s new owner makes significant newsroom cuts.
Sources told the Guardian that Pearson – firmly on the right of the Telegraph’s roster – is preparing to announce her exit imminently and is crafting a statement about her future plans.
Mohamed Amersi is suing over Panorama episode that made claims of his suspected involvement in corruption
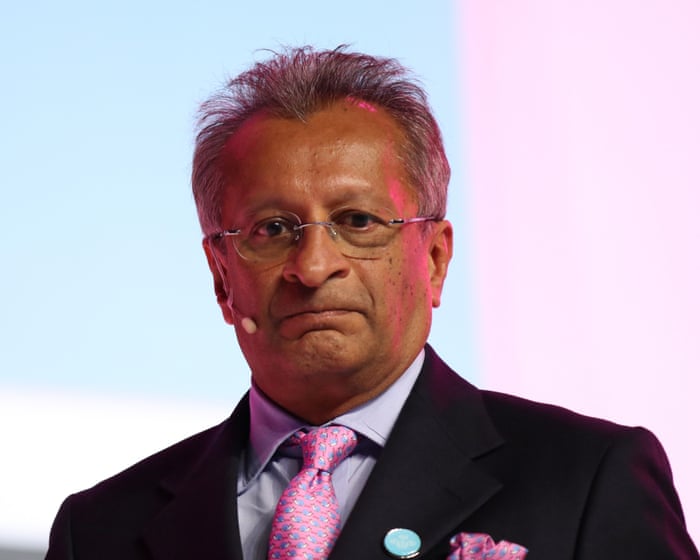
A Conservative and Reform UK donor lost out on a knighthood and a peerage amid claims of his involvement in corruption, the high court has heard at the start of his defamation case against the BBC.
An episode of Panorama in 2021 and a BBC article caused “very serious harm” to Mohamed Amersi, his barrister, Oliver Powell, said on Wednesday.
Judge says he will consider all options when sentencing far-right activist who trial heard deployed ‘bullyboy, intimidatory tactics’
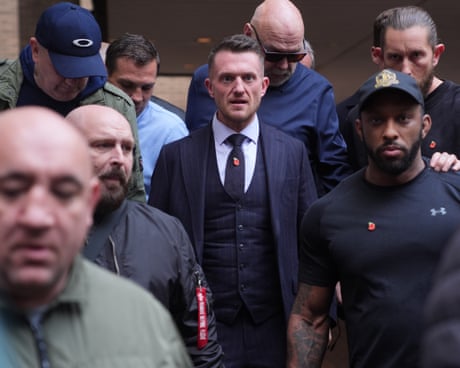
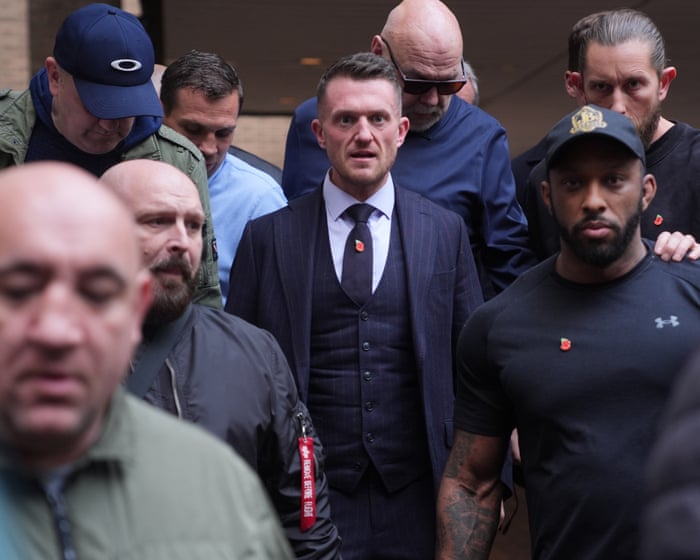
Tommy Robinson faces up to 10 years in prison after being found guilty of harassing two journalists to the point it caused them fear of violence.
Journalists from the Daily Mail and their family members fled their homes after “bullyboy, intimidatory tactics” were deployed by the far-right activist, whose real name is Stephen Yaxley-Lennon, his trial was told.
Warnings of escalating clampdown on press freedom come after Cairo court convicts Attalah of managing an unlicensed website
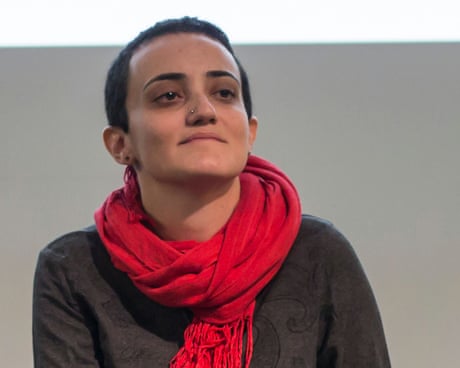
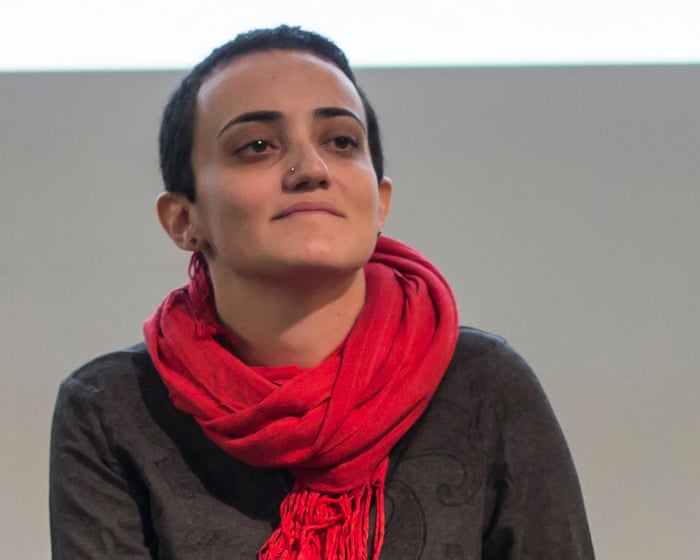
Lina Attalah, a prominent Egyptian journalist and the editor-in-chief of the news outlet Mada Masr, has been released from detention by Egypt’s authorities and had her website ordered to be shut down by a court amid an intensifying crackdown on independent media in the country.
Attalah was taken briefly into custody after a Cairo court convicted her of managing an unlicensed website, prompting fresh international concerns over press freedom in Egypt.
It feels like the skies above our AI-frenzied world have darkened in the past month. Employees at Anthropic and Google startedquitting, citing fears that the AI was spiraling out of control. After a string of agents started hacking websites, researchers used AI to discover vulnerabilities in critical systems, leading to large swaths of the web going dark last week and giving rise to a scary term: Black October. At the same time, as it continued to ramp up AI spending, Microsoft offered buyouts to 60,000 employees — over a quarter of its workforce — and economists once againwarned of a bubble.
It’s hard to reconcile the incongruity between the recent bad news and good news. For most of us, the state of AI is anxiety-inducing — especially when it comes to our livelihoods. According to a Pew Research Center study published in August, 71 percent of Americans think AI will lead to fewer jobs in the next two decades. That figure is up 7 percentage points from where it was two years ago. Sure, in the best-case scenarios, AI could erase inefficiencies at work, streamline our daily lives, cure diseases, and generally improve the human condition.
But what if you are the “inefficiency” at work that gets erased?
That tension is at the heart of Ethan Mollick’s latest book Co-Existence: The Next Phase of AI. If there is such a thing as an AI sage, it would be Mollick, an associate professor at the Wharton School and faculty director of its Generative AI Labs. To the nearly half a million subscribers to his Substack newsletter, One Useful Thing, he delivers semiweekly updates from the jagged frontier of the technology’s development. His message in any medium is resoundingly clear: You need to use AI in order to understand it. And to get the most out of using it, he argues that you have to accept that AI is not going away; it’s only going to become more important.
That ethos doesn’t make the existential threats of AI any less daunting, but that’s not the point. Unless you’re an early Anthropic employee or a United States senator, there’s probably not much you can do directly to rein in AI’s potential harms. But you can, according to Mollick’s worldview, decide how the technology could fit into your life and think about how you fit into an AI-dominated future.
I recently spoke with Mollick about his new book, what life and work might look like in the agentic AI era, and what it means to be an artisan when even knowledge is industrialized. His theories about living with AI are meant to help you navigate the future, regardless of the latest forecast. This interview has been lightly edited for length and clarity.
We’re entering a new era for AI, and the vibes are different. AI agents are something that many of us will encounter, interact with, and maybe even embrace. I’ve always known you as someone who jumps on the cutting edge of this technology to figure out what it can do. What do you think most people don’t understand about the next generation of AI?
I really think people haven’t internalized what agents do. Agents mean many things, and we can talk about personal agents, like Muse. But the fact that the problems that plagued working with AI agents before — you had to guide them each step of the way, they made mistakes, hallucinated constantly — that’s kind of gone. You can regularly get hours, days, weeks of work out of a system.
It’s not just a theoretical thing anymore. I talk to coders all the time who are a hundred times or more productive than they were before. And in other fields, we’ve kind of moved past the theoretical discussion about AI being, “This is going to be a big deal,” to, “It’s here.” From a whole kind of co-intelligence perspective, we’ve gone from, “Here’s how we use AI and work with a chatbot back and forth,” to, “These systems are now doing real work in ways that matter to real people and are reshaping real fields for better or worse.” And if you’re used to using AI a year ago, if you’re not paying for one of these systems, it’s really easy to have lost track of what’s going on.
What about the practical, everyday ways that AI is disrupting our lives? And what do you think are the limits of that disruption?
So outside of the job world and homework cheating, I think life has changed only a little bit for people, partially because these systems were kind of complicated to use and you had to decide what you were using them for. But I think the advent of personal agents, like Muse and Dot, are going to lead to a very rapid change in a lot of ways.
Most people I know who aren’t experts who use these systems, like my parents, are using these things spontaneously. They’re finding that once you know how to prompt the AI to do something, it can do things spontaneously and come back to you because it has your email and everything else. Just as one example, I was unable to figure out how to cancel my standing $8-a-month wifi subscription from my airline, and I was like, figure this out. And it went to customer service, joined chats, then I have no idea what it did, but now I don’t have a subscription to wifi anymore, thank goodness.
“I deeply worry that if I de-skill myself entirely, I won’t even know how computers work.”
So there is this sort of lowering friction piece that’s super interesting, with good and bad elements to it. The bad side of lowering friction is both that every article gets written by AI, so there’s no human thinking in it anymore, and that companies don’t want 10,000 customer service agents coming to them demanding new things. So I think we’re just on the edge of seeing the mass change in everyday life. Right now, AI is a really good second opinion on everything. As agents become more popular, they start to take action.
How do you know when to let AI do the work, though? We know that offloading certain tasks to AI can make you worse at doing those kinds of tasks in the future. How do you take advantage of AI’s ability to do drudgery but also hold onto your own expertise?
If there’s a personal theme underlying Co-Existence, it’s that one. That is an incredibly hard choice to make, and we’re historically very bad at making it.
Students are the No. 1 case because they’re willing to offload homework because homework sucks and because the incentives for doing any piece of homework are terrible. But overall we need to do it to learn. So people offload that, but even if you’re trying to do the right kind of thing, like using AI only to help you learn and not to replace learning, it turns out that when chatbots are in assistant mode, as opposed to using them as a tutor, it feels like you’re learning even though you’re not. You feel like you’re in the loop even though you’re not. And so that assumes that we both know we want to offload and we do it intelligently and that we do it in a way that helps our long-term gain.
I am worried about us being able to do that. You have to draw lines for yourself about what skills matter to you or not, and you have to be thoughtful, in a way that we’re usually not, about what we’re giving up and what we’re not. Technology’s designed for us to give up stuff. We don’t walk 50 miles a day anymore in forced marches. I don’t know how to weave clothes. There’s a lot of stuff I’m very happy to not know: how to maintain my computer in some ways, even though that’s dangerous. I let Codex scan for security issues because it does a better job than me faster. But I deeply worry that if I de-skill myself entirely, I won’t even know how computers work.
So I don’t have an easy answer, but I think that that will be the defining question for most people in their career paths right now and their lives: What do I give up? I think we can be too sentimental about things that we’re giving up. It’s okay, but we don’t know the full chain of consequences. I think that struggle is going to be central to a lot of people’s experience. I wish I had an easy answer, but now that AI can do so many things, de-skilling is a real problem at this point.
We’re living through a huge transformation. That’s increasingly clear. Besides losing their jobs, a lot of people are scared of losing the sense of what makes them human and what makes them valuable. How do people hold onto that in the years to come?
There’s a transformation happening, and for some people, the work will get more satisfying. There’s a lot of coders who did not like writing lines of code, but they did like summoning software and figuring out what they wanted to build. Their lives are much better because the AI does all the tedious work. They can command things to be built, and it’s so much more exciting than it was before. It lets people who didn’t code start to do incredible coding projects. So on one hand, that’s deeply freeing of the kinds of work that we did. On the other hand, there are people who love writing those lines of code and that’s gone now. You’re a hand-weaver in a world of power looms. Your stuff might be elegant and beautiful, but it is not going to last in a world where industrialization happens.
Industrialization versus craft is a way to think about this. There’s a lot of craft that we’ve grown to really appreciate, like the handcrafted sentence. Those things will be under threat from the logic of industrialization, which is that we need to do more of it. I think that there’s going to be a shift. There’s satisfying work to do, but I think a lot of what was satisfying human work will be under pressure to disappear, because you took pleasure in something that was not automatable, but now is.
We’ve been through this in industrial revolutions before. This is happening at a very large scale to intellectual work, where craft was a very important part of what we did. Mathematics was craft, software engineering was craft. I think that we’ll be under pressure to produce more of it, which is what industrialization’s about, even if that destroys the value of doing this as a person. You get paid to do it now, but you’re not getting the same value you did before.
“We’re no longer in a place where AI is going away.”
I think we’re going to find lots of crises of meaning. Some people are going to find huge amounts more meaning in their work, either because the work itself is now much more interesting. Work is a lot of crap, too. We can say great things about it, but people spend a quarter of their work life saying they’re bored. It’s not like this was a great job for everybody. So some people will have much more excitement in craft. Some people will have it extracted out of their job, and it’s all going to be happening at once. I know it’s not a satisfying answer, but that’s what’s happening.
Forgive me for saying so, but that was an anxiety-inducing answer. It’s an anxiety-inducing time. I wonder what advice you have for us anxious people?
I think anxiety is real, and there’s different levels of anxiety. We’re going through a wrenching change, or we will be going through one that we’re on the edges of now. There is also existential risk about whether AI will kill us all, where we clearly need more regulation. The answers are unclear. Smart people seem to think that that’s a real danger. It’s hard to know. But leaving that aside, there’s anxiety about our own transformation, our jobs. I mean, the industrial revolutions worked out great in the end, but during it, [that] was the time of Marx and anarchists and Dickens writing about London. There’s a transition we have to go through here.
I don’t think we can pretend it’s not happening, and I see a lot of people taking comfort in the idea that maybe this all will collapse and AI will go away. Even if there was a bubble financially, we’re no longer in a place where AI is going away or stopping development. I worry a lot about people doing that. Once you face that, though, I find people often reconstruct meaning in very exciting ways. Thinking about what more you can do and where you find joy in this is actually quite exciting. So I think that anxious optimism is a reasonable place to be.
What I worry about is sticking your head in the sand saying, “I’m not going to learn AI. This will go away. I’m going to pretend it’s not happening.” I mean, I wish I could give you that option. I think there’s a lot of people who wish we could slow things down or turn a dial down, but there’s also a lot of exciting things. There’s a lot of hard problems in the world that are unsolved.
If you lean into the positive pieces, you can ask how we mitigate risk but also think about how we can build a better world. Part of what makes me nervous is people sitting out that second question and just filling up with anxiety rather than believing we have a tool that can rebuild things. How do we rebuild a better world for journalism or for nonprofits or whatever it is? I think it’s a reasonable question to ask, and I worry it’s asked too little.
More than a dozen news organizations have asked a federal judge to unseal documents related to a search warrant executed at Ms. Omar’s home this month.
Experts say symptoms such as dark circles under the eyes, grey skin, cracked lips and hair loss can be a warning sign – but there are other factors too
TikTok is rife with influencers warning of “ferritin face”, a term they use to describe the pallor, dark circles, dry skin, and hair loss claimed to indicate low iron stores. But is this based on fact or fiction, and when is it time to head to the GP?
Supporters of the opposition movement that won Sunday’s election stormed the offices of a pro-government tabloid. Another news outlet apologized for years of “one-sided” coverage.
Six takeaways from a new memoir by Mr. Woodward, the star Washington Post reporter, including his disappointment with the newspaper’s billionaire owner.
President Luiz Inácio Lula da Silva won another term on Sunday, with the help of a seismic social media campaign that convinced Brazilians to reject his rival.
President Luiz Inácio Lula da Silva’s army of supporters, mobilized over a WhatsApp chat group, delivered an unexpected victory over Flávio Bolsonaro, the right-wing challenger.
In the increasingly bitter legal standoff between President Donald Trump and media outlets whose reporting he dislikes, a new and crucial third party has emerged: citizens who watch and read the news and need it to do their jobs.
Copper prices are at record highs, but for TikTok creators, the real money may be in teaching others how to strip wire—and selling them the tools to do it.
Luiz Inácio Lula da Silva, the leftist incumbent, and Flávio Bolsonaro, the right-wing challenger, face off in a narrow race that could redefine the future of Latin America.
“I knew there was a really good possibility that this would happen,” Blake Miley said. “But I don’t blame myself. It is not right what they did to me.”
A complaint I hear a lot from my millennial peers is that our parents didn’t teach us enough about money. I can say that personal finance wasn’t dinner table conversation in my house, and even as I went off to college and started fending for myself, it was almost a taboo subject. When it came to money, people either had it or they didn’t, and you definitely didn’t talk about it.
Maybe this is why the average American isn’t exactly fluent in personal finance, and the situation is getting worse. Americans can only answer about 50 percent of basic questions about borrowing, savings, and risk on a financial literacy survey, according to a 2026 study by TIAA, a retirement services company. About a third of those surveyed said they have a hard time making ends meet and are debt-constrained. These figures have remained relatively unchanged for nearly a decade, but dropped to their lowest level in this year’s study.
It makes sense: It’s hard to learn about money when it’s not taught in schools, and it’s such an intensely private topic. It’s also hard to make good financial decisions when you’re one of the growing number of American households struggling to pay bills, repay debts, and save for the future — and feeling very stressed about it.
In a perfect world, each of us could sit down with a financial adviser to get help — but most of us can’t afford that. Instead, average Americans tend to find personal finance tips on TikTok, in Reddit threads, by watching Suze Orman on YouTube or How to Get Rich on Netflix, or by Googling their questions.
Now we have AI tools, too.
With access to an internet’s worth of information and financial advice, ChatGPT, Claude, and other AI chatbots can answer any question you ask. They can help you put together a basic budget or, armed with your bank statements and the details of your student loans and your retirement accounts, tailor solutions to your specific situation. Or, at least, that’s the promise.
Key takeaways
More people are turning to AI for financial advice:One in five Americans have used AI to help manage their money, and some experts think chatbots could be better than the status quo.
AI works best if you know what questions to ask: Those with basic financial literacy will be able to make the most of these tools, while those without it — who might need help the most — could be led astray.
Better advice comes with greater risks: Sharing your financial information with a chatbot helps personalize its recommendations. This raises privacy concerns, so you might want to delete your data when you’re done.
Think of AI as a financially savvy friend:Chatbots can answer money questions you might be embarrassed to ask someone else and use that context to help build your budget.
AI could create a more utopian, more equitable future, where reliable, hyper-personalized advice is just a prompt or two away for people who can’t afford to meet with an expert in real life. But machines are built by people, and there’s good reason to be concerned that these machines will simply replicate the biases and disparities built into our current system.
Here’s what experts say about how to make the most of these tools — and how to think about all of the inherent risks of uploading a lot of personal financial information to a chatbot or, worse, giving an AI agent the keys to your bank account.
The steep rise, risks, and rewards of AI financial advisers
Nearly 20 percent of Americans have used AI tools like ChatGPT for financial advice, and close to 25 percent for Gen Z adults and millennials have tried it, according to an August Gallup poll. These numbers could tick up too: In October, OpenAI started rolling out a dedicated personal finance tool to its ChatGPT Free and Go users in the United States, which effectively means anyone can try it. ChatGPT Finances lets you securely connect your bank account to the tool using a platform called Plaid, and then you can basically have a conversation with the chatbot about your real-time finances down to the penny. It’s like an AI-powered Mint (RIP) that you can talk to directly.
Regardless of where you encounter a chatbot or how much data you give it, experts say these tools could genuinely help improve financial literacy. You can talk to them about money problems you’re too embarrassed to discuss with friends and family, or ask questions and receive actionable, personalized information. There are real upsides to using AI this way.
Taha Choukhmane, an associate professor of finance at the MIT Sloan School of Management, has been studying outcomes when people turn to chatbots for financial advice. In general, these AI tools give pretty good advice, and that advice gets better as people become more practiced in asking the right question, according to research he published earlier this year.
“We were actually quite surprised that relative to the status quo, the average American would be better off if they were to follow the advice,” Choukhmane told me. But he added a caveat: “Just following the advice without understanding the advice puts you at risk of not fully understanding the risk.”
But you shouldn’t trust everything a chatbot tells you and should verify everything before making any decisions.
Chatbot advice has some significant limitations. First, it’s not impartial. The finance industry has a vested interest in steering you toward certain ways of managing your money, and that typically means selling you products, like loans. If you’ve ever searched for personal finance tips on Google, you’ve probably noticed that a lot of the top results come from banks and other financial institutions. This is by design, according to John Campbell, an economics professor at Harvard. But because AI is aggregating all of that advice, the specific influences and possible bias is less obvious.
“AI is very promising for providing low-cost financial advice in plain English that will arguably be better than what many people would be able to do on their own,” said Campbell, who’s also the co-author of Fixed: Why Personal Finance Is Broken and How to Make It Work for Everyone. “One caveat is that chatbot advice is quite likely — unless a model has been carefully trained — to reflect the average of whatever’s being posted on the internet, and that may or may not be first-rate advice.”
An example Campbell gives is the question of when to start taking Social Security benefits. While you’re eligible at age 62, many economists agree that you should delay your benefits, which, based on the way the government calculates your monthly payouts, will allow you to enjoy much higher benefits later in life. But paid financial advisers can recommend starting as early as possible, since waiting longer reduces the amount of money that needs to be managed, which reduces the adviser’s fees. That means there’s a lot of conflicting advice online, much of it supplied by the finance industry. And that’s the information used to train AI models.
“The advice is much more mixed,” Campbell said. “And so if a chatbot is learning from that, it may not actually give the best advice.”
It can be hard to recognize bad advice anywhere in life, but especially when you’re talking to a machine that’s programmed to please you. A chatbot could encourage you to consider a balance transfer, to lean in on credit card rewards, or to refinance your mortgage — all decisions with upsides and downsides for you, but definite upsides for banks — without you realizing how much of its training data comes from the finance industry selling these products. What’s worse is that if you do end up taking bad advice, it might be years before you realize it. You won’t know that you refinanced a mortgage at a bad time until a better time comes along.
That leads me to the other major issue with using chatbots for money advice: People who lack financial literacy are the most likely to fall for bad advice, because they simply don’t recognize it as such. They also tend to be less wealthy, which means they can’t afford big mistakes.
One way to mitigate risk, oddly enough, is to give the AI chatbot more personal information. The more details about your situation it has to consider, the more it can offer personalized advice. More context also means better advice, according to Choukhmane.
“There’s a trade-off there,” Choukhmane said. “There’s real risk around privacy, and so I think everyone needs to find their level of control.”
Don’t assume your data is safe
Any time you’re talking to a chatbot, you’re putting a lot of trust in tech companies to take care of the personal details you’re sharing. Sending sensitive financial data is an especially risky proposition. While tech companies, including OpenAI, promise to keep your data secure, there’s already a long list of breaches, leaks, and privacy violations that serve as cautionary tales.
It’s also impossible to know what tech companies might do with your data in the future. Most of them will use it to train their models, unless you tell them not to. Some of them will use the data to serve you personalized ads.
Then there’s the risk of bad actors getting into your ChatGPT, Claude, or Gemini account. If you’ve been using a chatbot for financial advice and uploading your bank statements, a hacker could gain access to a stunning amount of information that could enable them to do all kinds of terrible things to your life.
“They could steal your identity and open accounts and then quickly bankrupt a person,” said Delicia Reynolds Hand, a senior director at Consumer Reports. “It’s not even so much the primary underlying accounts that could be at risk, it’s more just access to this information.”
The steady march of AI progress is making this situation even more complicated. The previous era of chatbots offering financial advice is quickly bleeding into a new phase of AI agents logging into bank accounts on users’ behalf. If you’re using a tool like Claude Cowork or even an AI assistant like Muse, you can give an agent the login credentials to your bank account, and because the agent is operating its own computer, it can actually make transfers, apply for loans, or really do anything in your account. This is reportedly driving major banks wild, since they don’t know which logins are coming from humans and which are agents. And because we know that AI agents are unpredictable, it’s hard to know how that access might go wrong.
Beyond data security and privacy, you should also be aware of the simple fact that nobody’s really at fault if you end up losing money using these tools. Chatbots are not regulated in the way that human financial advisers, who have a fiduciary duty to act in your best interest, are.
“If I get bad tax advice from H&R Block or a tax adviser, there are a clear set of rules and guardrails in place to manage what I can expect in that relationship and where the service they use has liability and where that liability ends,” Hand said. “Currently, that’s not the case for these tools.”
Trust but verify — and then delete your data
In the final years of the Cold War, Ronald Reagan popularized an old Russian proverb: Trust, but verify. The phrase is somewhat nonsensical, since trusting someone implies that you don’t need to verify what they’re saying, and verifying what’s said implies you didn’t trust them in the first place. But if you are willing to shoulder a bit of risk, consider approaching AI this way, especially when your life savings are on the line. I’d also suggest adding a coda to the phrase: And then delete your data.
Chatbots are not stand-ins for licensed financial advisers, he said, and you shouldn’t let them make decisions for you.
The great paradox with tools like ChatGPT and Claude is that they’re very good at generating truthy text. It sounds authoritative and looks correct — and usually is. Except when it isn’t. AI is famously unpredictable and prone to hallucinations. You can ask the same question twice and get two different answers. That doesn’t mean these tools are useless. It just means you have to approach them with caution. You have to interrogate these chatbots, challenge whatever advice they give you, and then crosscheck that with other, more reputable, sources.
“If you’ve never used these tools, I would not encourage you to just change all your financial plans based on your first conversation,” Choukhmane said. “You want to be quite careful. Start using these tools, start understanding, ask a lot of follow-up questions.”
When it comes to mitigating risk, consider giving ballpark figures for your income or spending when you’re talking to a chatbot about your finances. Uploading financial documents, even if they’re redacted, is inevitably filling a tech company’s vault with your sensitive information without necessarily knowing what will happen to it next. You should also dig into your privacy and security settings to make sure you’ve turned on multi-factor authentication and that your personal data is not being used to train AI models and gets deleted after 30 days.
Ethan Bloch, the product lead for ChatGPT for Financial Services, made a similar set of recommendations when I talked to him recently. Chatbots are not stand-ins for licensed financial advisers, he said, and you shouldn’t let them make decisions for you. They’re designed to inform and help you think through complex topics.
“You should liken it to just talking to a friend who has some very informed opinions about finance,” Bloch told me. “But if you’re actually making some large financial decision — your portfolio or retirement — you still need to seek out the help.”
Regardless of how experienced you are with chatbots or how much data you’re prepared to hand over, remember what Campbell, the Harvard professor, said. If your financial literacy isn’t great, AI chatbots can be trouble. And if you’re like most Americans, you could probably stand to learn a little bit more about things like mortgages and interest rates.
Yes, Chatbots can be a good way to brush up on financial literacy. You can ask them the money questions you’re too embarrassed to discuss with friends and family. But you can also learn about money the old-fashioned way: Reading books and websites written by reputable, independent sources. The Federal Deposit Insurance Corp. has a portal of financial education resources, including games and quizzes. Khan Academy has a course that covers everything from credit scores to college savings. There’s a personal finance subreddit that I joined years ago and read almost daily. There are budgeting apps, like YNAB which has its own huge Reddit presence.
Whatever you do to learn more about personal finance, simply doing something is progress. Talking about personal finance isn’t the taboo it once was in the US, and it’s even a required course in the vast majority of American high schools now. And while AI won’t magically solve your money problems, it can help get you started. Just be careful. Your livelihood could be on the line.

 Login